

Blockchain has become one of those terms that gets used constantly in technology and finance conversations without always being clearly explained, often mentioned alongside cryptocurrency in ways that make the two concepts feel more inseparable and confusing than they actually need to be.
The fundamental concept behind blockchain technology, separate from any specific application like cryptocurrency, provides a clearer foundation for evaluating both its genuine capabilities and its actual limitations.
What a Blockchain Actually Is
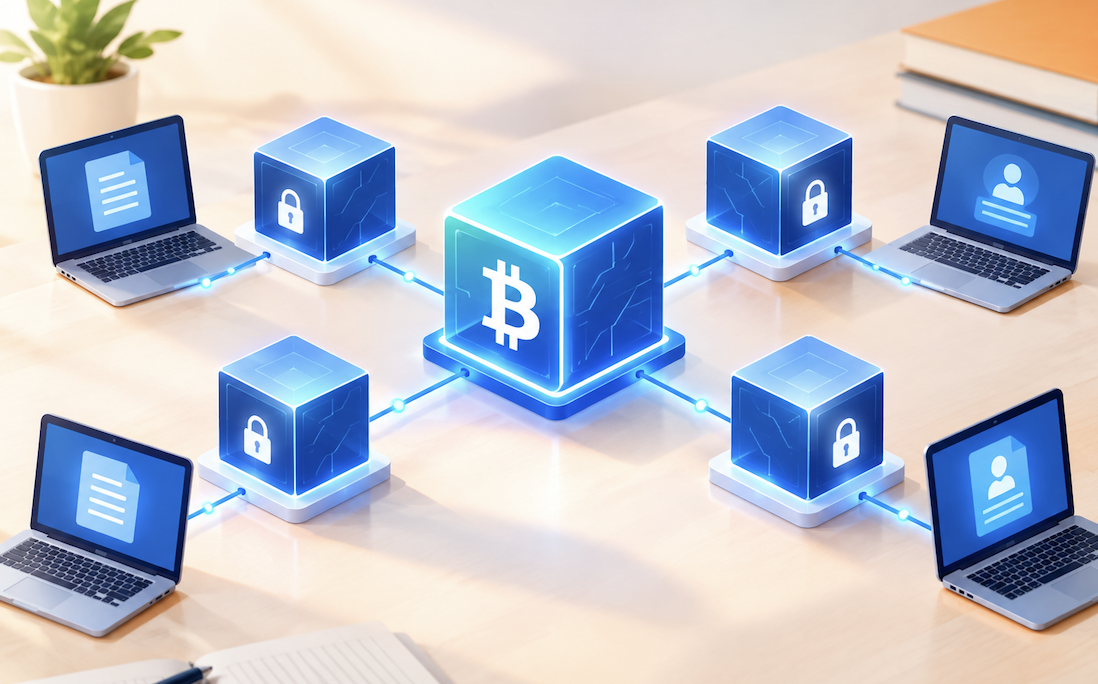
At its core, a blockchain is a specific type of database, a way of recording and storing information, that’s structured differently from a traditional database in a few important ways. Rather than being stored and controlled by a single central authority, a blockchain is distributed across many different computers, sometimes called nodes, that each maintain a copy of the same record.
Information is added to this record in groups called blocks, and each new block is cryptographically linked to the previous one, forming a chronological chain, which is where the technology gets its name.
This structure creates a record that’s extremely difficult to alter after the fact, since changing information in a previous block would require also changing every subsequent block linked to it, and doing so across every single copy distributed among all the participating computers simultaneously, which becomes computationally impractical as the chain grows longer and more computers participate in maintaining it.
Why Decentralization Matters
The genuine innovation behind blockchain technology isn’t simply the chain-of-blocks data structure itself similar concepts have existed in computer science for a long time, but rather the combination of this structure with a decentralized network where no single party has unilateral control over the entire record.
In a traditional centralized database, a bank’s internal record of account balances, for example, that single organization has complete control and could theoretically alter records unilaterally, though obviously subject to legal and regulatory oversight in practice.
A properly decentralized blockchain removes this single point of control, requiring changes to be validated according to rules the network’s participants have collectively agreed upon, rather than depending entirely on trust in a single central authority to maintain accurate, unaltered records. This is genuinely valuable specifically in situations where participants don’t necessarily fully trust each other or a single central authority, but still need to maintain a shared, reliable record of information or transactions.
How Consensus Mechanisms Work
For a decentralized network to agree on what information is legitimately added to the blockchain, various consensus mechanisms have been developed, essentially rules determining how the network agrees on the current, valid state of the shared record. Proof of work, used by Bitcoin among others, requires participants to solve computationally intensive mathematical problems to earn the right to add the next block, making it prohibitively expensive for any single party to gain enough control to manipulate the record fraudulently.
Proof of stake, used by many newer blockchain systems, instead requires participants to commit, or stake, a certain amount of the network’s native currency as collateral, with the right to validate new blocks distributed based on this staked amount, generally requiring less energy consumption than proof of work systems.
That these are simply different technical approaches to solving the same underlying problem how a decentralized network agrees on what’s true without a central authority helps demystify some of the more technical blockchain discussions you might encounter.
Blockchain and Cryptocurrency Are Related but Distinct Concepts
Cryptocurrency represents one specific, prominent application of blockchain technology, using it to maintain a decentralized record of currency ownership and transactions without requiring a central bank or financial institution.
However, blockchain technology itself is a more general tool that can theoretically be applied to numerous other use cases beyond currency specifically, and this distinction helps clarify that skepticism about a specific cryptocurrency’s value or legitimacy doesn’t necessarily equate to skepticism about blockchain technology as a broader technical concept, and vice versa.
Other Applications Beyond Cryptocurrency
Supply chain tracking represents one area where blockchain’s tamper-resistant, transparent record-keeping has found genuine practical application, allowing multiple parties across a complex supply chain, manufacturers, shippers, retailers, to maintain a shared, trustworthy record of a product’s journey without requiring complete trust in any single party’s internal record-keeping system.
Smart contracts, self-executing agreements with terms directly written into code that automatically execute when predetermined conditions are met, represent another significant application, potentially reducing the need for intermediaries in certain types of agreements and transactions by automating execution based on verifiable, predetermined conditions rather than requiring manual verification and enforcement by a trusted third party.
Digital identity verification, land registry systems, and voting systems have all been explored as potential blockchain applications as well, though many of these remain in earlier stages of development and adoption compared to cryptocurrency’s more established, widespread use.
Understanding the Genuine Limitations
Blockchain technology, despite its genuine strengths, isn’t a universally superior solution for every data storage or record-keeping problem, and its actual limitations provides a more balanced
perspective than either uncritical enthusiasm or blanket dismissal. Blockchain systems, particularly proof-of-work based ones, can be significantly slower and more resource-intensive than traditional centralized databases for many applications, since achieving the decentralized consensus that provides blockchain’s core security benefit requires more computational overhead than a simple centralized database update.
Additionally, for many applications, the specific problem blockchain solves, removing the need for trust in a single central authority, simply isn’t relevant, since a trusted central authority, a well-regulated bank, or a well-established company’s internal database already exists and functions perfectly well for that particular use case without needing blockchain’s specific decentralized architecture.
Evaluating Blockchain Claims Skeptically
Given blockchain’s prominence in recent technology and business discussions, it’s worth applying genuine scrutiny to specific claims about blockchain applications, evaluating whether a proposed use case genuinely benefits from blockchain’s specific properties, decentralization, tamper resistance, removing the need for trust in a central authority, or whether blockchain is simply being used as a marketing term without a genuine underlying technical justification for that particular application.
Asking specifically what problem a proposed blockchain application is actually solving, and whether that problem genuinely requires blockchain’s specific properties rather than being solvable more simply and efficiently through a traditional centralized database, helps cut through some of the hype that has sometimes surrounded blockchain technology discussions in recent years.
Conclusion
Blockchain as fundamentally a decentralized, tamper-resistant record-keeping technology, separate from any specific application like cryptocurrency, provides a genuinely useful foundation for evaluating both its legitimate applications and the sometimes overstated claims made about its capabilities.
This foundational matters increasingly as blockchain-related discussions continue appearing across technology, finance, and business contexts, allowing you to engage with these discussions from a place of genuine rather than either uncritical enthusiasm or dismissal based on unfamiliarity with the actual underlying technology.
FAQ’s
Is blockchain the same thing as cryptocurrency?
No, though the two are closely related. Cryptocurrency is one specific application built using blockchain technology, but blockchain itself is a more general data structure and consensus approach that can theoretically be applied to many different use cases beyond currency, supply chain tracking and smart contracts, among them.
Can information on a blockchain ever actually be deleted or changed?
Generally, no, which is precisely the point of the technology’s design. Once information is recorded and confirmed across the distributed network, altering it would require simultaneously changing every subsequent linked block across every copy of the chain maintained by participating computers, which becomes computationally impractical as the chain grows. This immutability is a core feature, though it also means genuine errors recorded on a blockchain can be difficult or impossible to correct after the fact.
Why does blockchain sometimes get criticized for its energy usage?
This criticism applies specifically to certain consensus mechanisms, particularly proof of work, which require significant computational effort and corresponding energy consumption to validate new blocks and maintain network security. Newer consensus mechanisms, particularly proof of stake, have been specifically developed partly to address this concern, requiring less energy meaningfully while still maintaining decentralized security, though they involve different tradeoffs worth considering for anyone evaluating a specific blockchain system.
Do businesses actually use blockchain for anything beyond cryptocurrency today?
Yes, though adoption varies considerably by industry and specific application. Supply chain tracking, certain financial services applications, and some specific smart contract implementations have seen genuine practical adoption, though many other proposed blockchain applications remain more experimental or haven’t achieved the same level of widespread practical use as cryptocurrency has.
Is it worth learning more about blockchain if I’m not interested in cryptocurrency investing specifically?
The basic concepts can be genuinely useful given how frequently blockchain-related topics appear across technology, business, and even some policy discussions, independent of any personal interest in cryptocurrency as an investment. A general conceptual understanding, rather than deep technical expertise, is sufficient for most people to meaningfully engage with these broader conversations and evaluate specific claims more critically.
What’s the difference between a public and private blockchain?
A public blockchain is open for anyone to participate in, view, and, in some cases, help validate, with Bitcoin serving as a well-known example. A private or permissioned blockchain restricts participation to specific, approved parties, often used in business contexts where full public access isn’t desired but the underlying benefits of tamper-resistant, shared record-keeping among a defined group of trusted business partners are still valuable.
