

Wanting to travel and actually having the funds saved up to do so comfortably are two different things, and the gap between them often comes down less to income level than to having a clear, specific savings strategy rather than a vague intention to “save more” without any concrete plan behind it.
Building a realistic vacation fund, even on a modest budget, is entirely achievable once you approach it with the same intentionality you’d bring to any other meaningful financial goal.
Set a Specific, Concrete Target
Before you can effectively save for a trip, you need a number to work toward, not a rough guess but a researched, realistic estimate covering flights, accommodation, food, activities, and a reasonable buffer for unexpected costs.
Researching actual prices for your specific intended destination and travel dates, rather than relying on a vague general impression of what a trip “probably” costs, gives you a concrete target that makes the entire saving process considerably more actionable.
Breaking this total target down by your intended timeline, how much you need to save per month or per week to reach your goal by your desired departure date, transforms an abstract, sometimes intimidating total into a manageable, specific action you can actually track progress against consistently.
Open a Dedicated Savings Account
Keeping vacation savings in a completely separate account from your everyday spending money creates a meaningful psychological and practical barrier against accidentally spending funds intended for your trip on unrelated purchases.
Many banks now offer free savings accounts specifically designed for goal-based saving, sometimes even allowing you to name the account after your specific destination or trip, which provides an additional layer of visual motivation every time you check your balance and see tangible progress toward a goal you’re excited about.
A high-yield savings account, offering meaningfully better interest than a typical checking account, provides the added benefit of your money actually growing somewhat while it sits saved, rather than remaining completely stagnant, particularly valuable if you’re saving over a longer timeframe of many months or even a year or more.
Automate Your Vacation Savings
Setting up an automatic transfer from your checking account to your dedicated vacation fund, timed to coincide with each paycheck, removes the need to rely on willpower or memory to actually follow through on your savings goal consistently.
Even a relatively modest automatic transfer, twenty or thirty dollars per paycheck, for example, adds up meaningfully over several months, and the automation itself ensures this saving actually happens reliably rather than depending on remembering to manually transfer money whenever you happen to think of it.
Find Specific Expenses to Cut Temporarily
Rather than adopting an overwhelming, generally restrictive budget across your entire life, identifying a handful of specific, temporary cuts you’re willing to make until you’ve reached your vacation savings goal tends to feel considerably more sustainable and less deprivation-focused. This might mean pausing a streaming subscription you rarely use, reducing how often you order takeout, or skipping a few nonessential purchases you’d normally make without much thought.
Framing these adjustments as temporary and directly connected to something you’re excited about, an actual upcoming trip rather than an abstract savings goal, tends to make the sacrifice feel considerably more worthwhile and easier to maintain consistently than a vague, open-ended budget restriction without a clear, motivating endpoint.
Redirect Windfalls Directly Toward Your Trip
Tax refunds, work bonuses, cash gifts, and other unexpected windfalls represent an excellent opportunity to make significant progress toward your vacation fund without requiring any change to your regular monthly budget.
Since this money wasn’t already allocated to your everyday expenses, redirecting even a substantial portion of it directly into your vacation savings rarely feels like a sacrifice, since you weren’t counting on it as part of your regular spending in the first place.
Sell Items You No Longer Need
Many households accumulate items over time that no longer provide value but could be sold for meaningful cash, clothing you no longer wear, electronics you’ve upgraded away from, furniture or household items you no longer need.
A focused decluttering effort specifically aimed at generating vacation funds serves the dual purpose of reducing household clutter while directly contributing to your specific savings goal, and many people are surprised by how much accumulated, unused value they can convert into real trip funding through this approach.
Consider a Short-Term Side Income Specifically for Travel
If your regular income doesn’t leave much room for additional saving after essential expenses, a temporary side income specifically earmarked for your vacation fund, freelance work, selling a specific skill, a short-term gig, can accelerate your progress considerably compared to waiting for gradual savings from your existing income alone.
Treating this supplemental income as entirely separate from your regular budget, directing all of it specifically toward your travel fund rather than letting it blend into general spending, maximizes its actual impact on your specific savings goal.
Use Travel Rewards and Points Strategically
If you use credit cards responsibly, paying balances in full each month to avoid any interest charges, travel rewards programs can meaningfully reduce your actual out-of-pocket costs for flights or accommodation, effectively stretching your savings further than the cash amount alone would otherwise cover.
This strategy only makes financial sense if you’re not carrying a balance or paying interest, since any interest charges would quickly outweigh the value of rewards earned, but for those who use credit responsibly, this can meaningfully supplement your dedicated cash savings.
Book Certain Elements Early to Lock In Lower Prices
Once you’ve made meaningful progress toward your savings goal and have a reasonably firm sense of your trip’s timing, booking flights and accommodation earlier, when prices are often more favorable than closer to your actual travel date, can reduce your total required savings compared to waiting until the last minute.
This requires having accumulated enough savings to cover these upfront costs specifically, but strategically timing these larger purchases as your fund grows can meaningfully reduce your overall trip cost compared to booking everything at once closer to departure.
Track Your Progress Visually
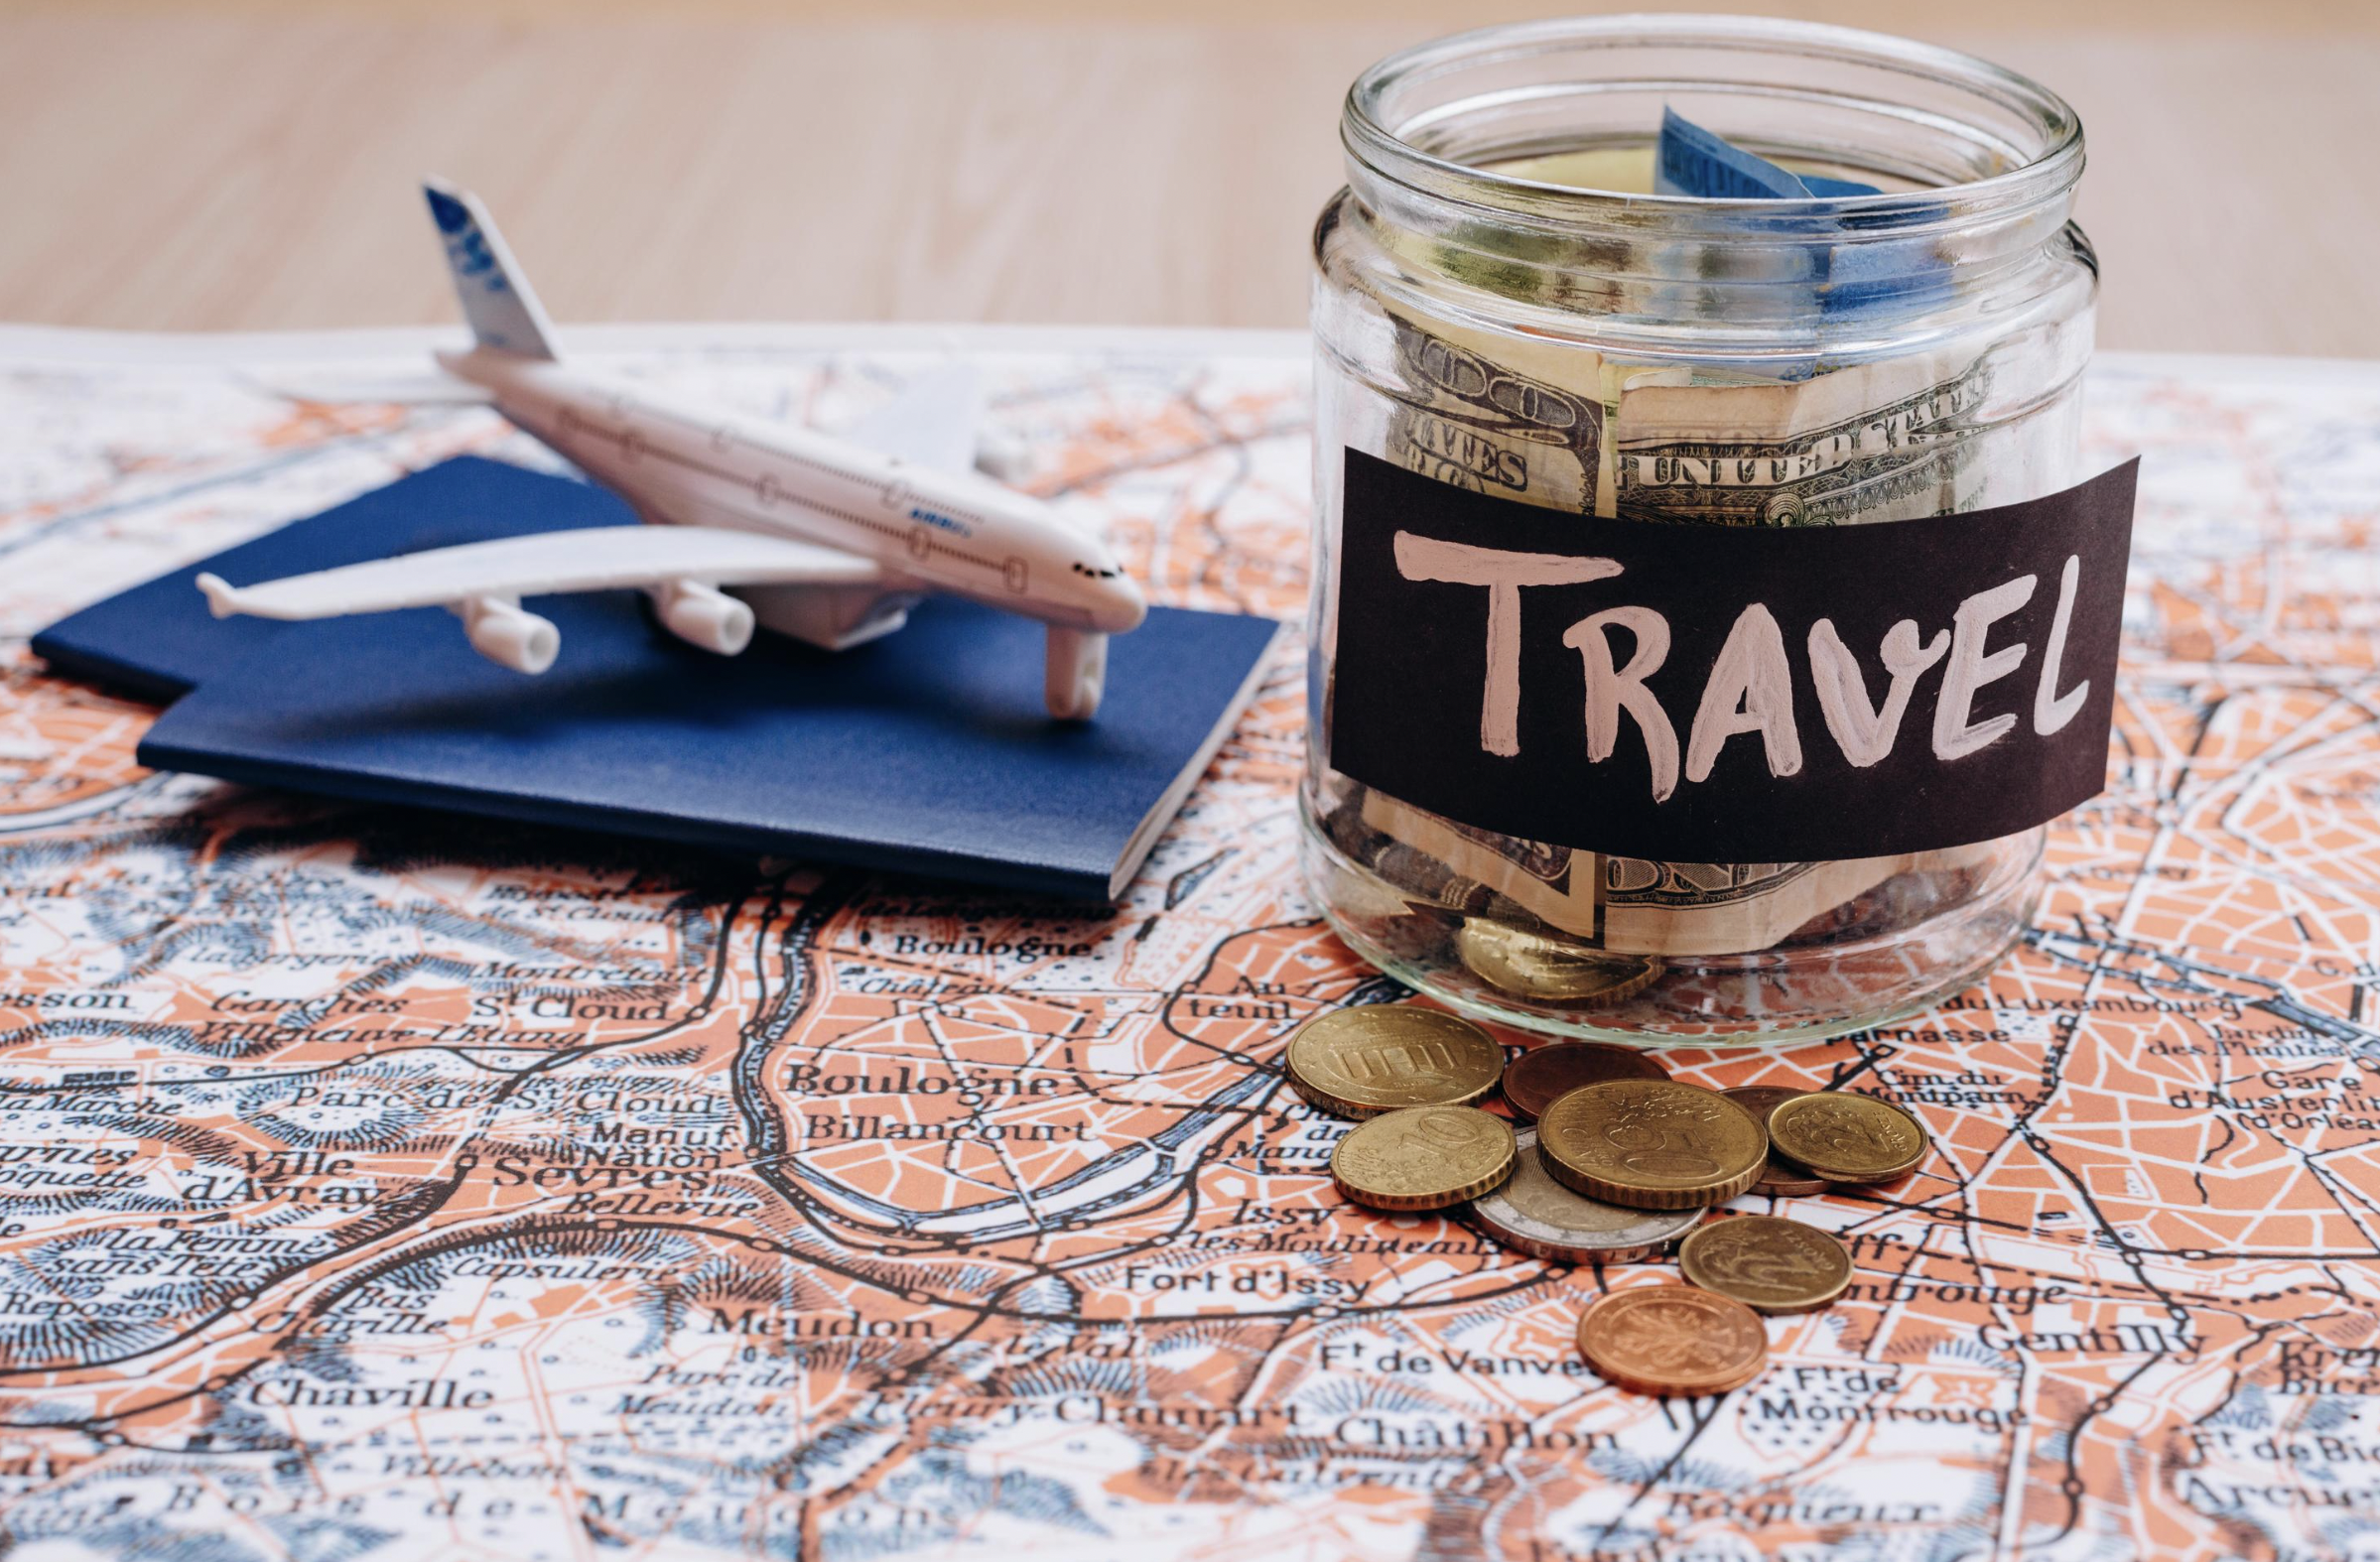
Seeing tangible evidence of your accumulating vacation fund, whether through your bank account’s own progress tracking features, a simple spreadsheet, or even a physical visual tracker like a jar or chart, provides motivation that abstract awareness of “saving for a trip” often doesn’t provide on its own.
Watching a specific number grow steadily toward your target transforms an extended saving process into something considerably more tangible and rewarding to actually witness unfold over time.
Build In a Reasonable Buffer
Beyond your core estimated trip costs, adding a reasonable buffer, generally somewhere around ten to fifteen percent of your total budget, protects against the inevitable unexpected expenses that arise during actual travel, a pricier meal than anticipated, an activity you hadn’t originally planned for but want to experience, or simple cost estimation errors in your original research.
Having this buffer already built into your savings target means these normal, expected variations don’t derail your trip financially or force uncomfortable choices once you’re already there and unable to easily adjust your budget further.
Conclusion
Rather than treating vacation savings as a one-time effort tied to a single specific trip, building the underlying habits, a dedicated savings account, automatic transfers, mindful spending adjustments, into an ongoing part of your regular financial routine makes saving for future trips considerably easier each subsequent time.
Once these systems are established and functioning smoothly, saving for your next vacation becomes less of a dedicated project requiring renewed effort and more simply a continuation of habits you’ve already built and refined through your first successful vacation savings experience.
Frequently Asked Questions
How long should I realistically give myself to save for a trip?
This depends on your specific target amount and available monthly saving capacity, but many people find that giving themselves at least six months to a year provides enough time to reach a meaningful goal without requiring drastic, unsustainable cuts to their regular budget. Shorter timelines are certainly possible for smaller trips or if you have more disposable income available to redirect, but a longer runway generally makes the process feel considerably more comfortable and sustainable.
What if I fall behind on my savings target partway through?
Adjusting your plan rather than abandoning it entirely is the better response, whether that means extending your timeline slightly, finding an additional temporary income source, or scaling back certain elements of the trip itself to match what you’re realistically able to save by your original departure date. A modified, achievable plan serves you better than either rigid insistence on an unrealistic original target or giving up on the goal altogether.
Is it better to save cash or rely primarily on travel credit card rewards?
A combination generally works best for most people, using dedicated cash savings as your primary funding source while letting responsible credit card use for regular expenses generate supplemental rewards that stretch your budget somewhat further. Relying entirely on rewards without adequate cash savings can leave you underprepared for the substantial portion of trip costs that rewards alone typically can’t fully cover.
Should I keep my vacation fund completely separate even from my emergency fund?
Yes, keeping these funds distinctly separate matters, since blending them risks either underfunding a emergency because money was earmarked for travel, or delaying a trip because funds intended for vacation got used for an unrelated financial emergency. Maintaining clear, separate accounts for each specific purpose helps ensure both goals remain protected and on track independently of each other.
What if my income varies significantly month to month, making automatic transfers unreliable?
Consider a percentage-based approach rather than a fixed dollar amount, directing a consistent percentage of whatever income arrives toward your vacation fund rather than a fixed sum that might not always be realistic during lower-income periods. This approach naturally scales with your actual earnings, helping maintain consistent progress even when your income itself isn’t perfectly predictable from month to month.
