

Travel insurance is one of those purchases people often make quickly, checking a box during flight booking or grabbing whatever policy comes up first in a search, without actually reading what’s covered. This approach frequently means discovering the gaps in coverage only after something has already gone wrong, at exactly the moment when a policy’s actual limitations matter most. Understanding what to actually look for before buying makes the difference between a policy that provides genuine protection and one that provides false peace of mind.
Understand the Main Categories of Coverage
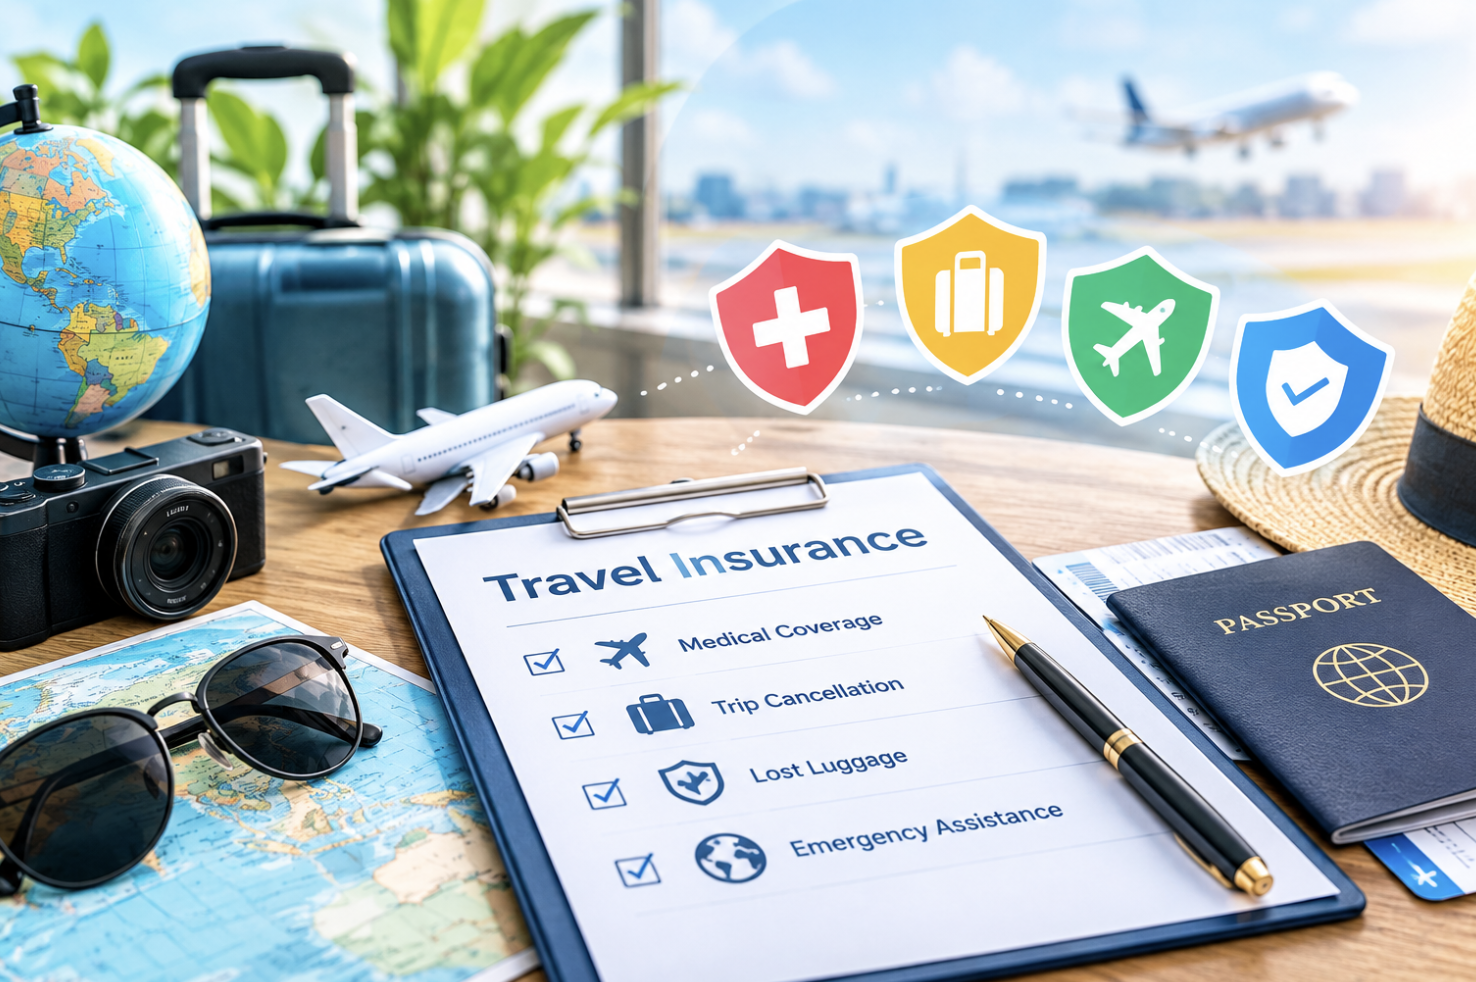
Travel insurance policies typically bundle together several distinct types of coverage, and understanding each separately helps you evaluate whether a specific policy actually meets your needs. Trip cancellation and interruption coverage reimburses you for prepaid, non-refundable trip costs if you need to cancel or cut short your trip for a covered reason, illness, a family emergency, or certain other qualifying circumstances specifically listed in the policy.
Medical coverage pays for healthcare costs incurred during your trip, which matters enormously for international travel specifically, since domestic health insurance frequently provides limited or no coverage outside your home country. Emergency medical evacuation coverage, often bundled separately or as an add-on, covers the potentially enormous cost of being transported to adequate medical care if you’re injured or become seriously ill somewhere without nearby appropriate facilities.
Baggage and personal item coverage reimburses you for lost, stolen, or damaged luggage and belongings, generally up to a specified limit. And some policies include coverage for trip delays, providing reimbursement for reasonable expenses incurred due to a significant delay, separate from full cancellation.
Match Coverage to Your Actual Trip and Risk Profile
Not every trip requires the same type or level of coverage, and understanding your specific situation helps you avoid both underinsuring and paying for coverage you don’t actually need. A domestic trip with fully refundable bookings might need minimal trip cancellation coverage but could still benefit from medical coverage if your regular health insurance has significant gaps or high out-of-network costs. An expensive international trip with substantial non-refundable prepaid costs, extensive activities, or travel to a region with limited healthcare infrastructure warrants more comprehensive coverage across multiple categories.
If you’re planning specific higher-risk activities, scuba diving, skiing, motorbike riding, it’s worth explicitly checking whether these are covered under a standard policy or require a specific add-on, since many standard policies exclude certain adventure activities by default, a detail easily missed without directly checking the policy’s specific exclusions.
Read the Pre-Existing Medical Condition Exclusions Carefully
This is one of the most commonly overlooked, and most consequential, details in travel insurance policies. Many policies exclude coverage related to pre-existing medical conditions unless you purchase the policy within a specific window after booking your trip, sometimes called a look-back period, and meet certain other conditions. If you have any ongoing health conditions, understanding exactly how a specific policy defines and handles pre-existing conditions, and whether you qualify for a waiver of this exclusion by purchasing promptly and meeting other requirements, matters significantly for whether the policy will actually provide the medical coverage you might need.
This is worth reading directly in the policy’s actual terms rather than relying on a general summary, since the specific definitions and waiver requirements vary meaningfully between insurers and policies.
Check the Coverage Limits, Not Just Whether Something Is Covered
A policy might technically include medical coverage, but the actual dollar limit matters enormously, particularly for international trips where a serious medical event or evacuation can easily cost tens of thousands of dollars or more. Comparing the specific coverage limits across policies, rather than simply confirming a category is included at all, reveals meaningful differences that a surface-level comparison would miss entirely.
Similarly, baggage coverage limits and any per-item sub-limits, often lower for individual valuable items like electronics or jewelry, are worth checking specifically if you’re traveling with anything particularly valuable, since a policy’s overall baggage limit doesn’t always apply fully to a single expensive item.
Understand What Counts as a “Covered Reason” for Cancellation
Trip cancellation coverage only reimburses you for cancellations due to specific reasons explicitly listed in the policy, not simply changing your mind or general anxiety about traveling. Common covered reasons typically include your own serious illness or injury, a serious illness or injury of a close family member, and certain other specific circumstances like jury duty or a natural disaster affecting your destination.
If you want broader flexibility to cancel for reasons not covered under a standard policy, look specifically for a “cancel for any reason” upgrade, often available as an add-on at additional cost, which provides broader, though still not unlimited, flexibility, typically reimbursing a percentage rather than the full trip cost, and requiring purchase within a specific window after your initial trip deposit.
Consider Whether You Need Standalone Insurance or Have Existing Coverage
Some credit cards, particularly premium travel rewards cards, include certain travel insurance benefits automatically when you book travel using that card, and it’s worth checking your specific card’s benefits guide to understand exactly what’s included and what the coverage limits are, since these built-in benefits vary enormously between cards and are often more limited than a dedicated standalone travel insurance policy.
If your existing coverage, through a credit card or other source, seems to already cover your specific trip’s actual risks adequately, a standalone policy may be unnecessary. If there are meaningful gaps, particularly around medical coverage and evacuation for international trips, a standalone policy specifically addressing those gaps may be worth the additional cost even if you have some existing baseline coverage.
Buy Early Enough to Access Full Benefits
Certain valuable benefits, particularly the pre-existing condition waiver mentioned above and cancel for any reason upgrades, typically require purchasing your policy within a specific window after your initial trip deposit, often within fourteen to twenty-one days depending on the specific insurer. Waiting too long to purchase travel insurance can mean losing access to these particular benefits entirely, even if you’re still within the policy’s general purchase window for basic coverage.
Read Reviews Focused Specifically on the Claims Process
A policy’s coverage on paper only matters if the insurer actually processes and pays claims fairly and promptly when something goes wrong. Researching reviews and complaint records specifically focused on the claims experience, rather than just the initial purchasing experience, gives you a more accurate picture of how a specific insurer performs when you actually need to use the coverage you’ve paid for, which is ultimately the entire point of having the policy in the first place.
Conclusion
Rather than choosing based solely on price or convenience, take the time to understand your specific trip’s actual risks, compare coverage limits and pre-existing condition policies across a few options, check for any existing coverage you might already have through a credit card, and research the claims experience specifically before committing.
This extra diligence upfront is what actually determines whether your travel insurance provides genuine protection when you need it, rather than simply providing a comforting sense of coverage that turns out to have significant gaps exactly when it matters most.
Read more about News PinUp
Frequently Asked Questions
1. Is travel insurance worth the cost for a relatively inexpensive domestic trip?
It depends on your specific situation. For a fully refundable, inexpensive trip with health insurance that already covers you adequately within your own country, the case for travel insurance is weaker. For a trip with significant non-refundable costs, or if your regular health insurance has meaningful gaps, even a domestic trip can benefit from at least trip cancellation and medical coverage.
2. Does travel insurance cover cancellations due to a pandemic or widespread health event?
This varies significantly by policy and by the specific circumstances, and many standard policies exclude cancellations related to known, foreseeable events rather than sudden, unexpected ones. If this is a specific concern, look for policies that explicitly address epidemic or pandemic-related cancellations, or consider a cancel for any reason upgrade for broader flexibility regardless of the specific reason.
3. How do I actually file a claim if something happens during my trip?
Most insurers require documentation supporting your claim, medical records for a health-related claim, a police report for stolen belongings, or airline documentation for a significant delay or cancellation. Keeping thorough records and receipts during your trip, and contacting your insurer as soon as possible after an incident occurs, generally makes for a smoother claims process than waiting until you’ve returned home to begin gathering documentation.
4. Can I buy travel insurance after I’ve already left on my trip?
Some insurers do offer policies purchasable after departure, though these typically come with more limited coverage and exclude anything that has already begun or occurred, like a pre-existing illness that started before you purchased the policy. Buying insurance before departure, ideally soon after booking your trip, provides significantly better coverage options and access to benefits like the pre-existing condition waiver that later purchases typically can’t access.
5. Is annual, multi-trip travel insurance worth it if I travel frequently?
For people taking multiple trips throughout the year, an annual policy covering all trips within that period can be more cost-effective than purchasing separate policies for each individual trip, provided the annual policy’s coverage limits and terms genuinely fit your typical travel patterns. It’s worth comparing the total cost of an annual policy against what you’d realistically spend on individual trip policies for your actual travel frequency before committing to either approach.
