

Individual retirement accounts offer meaningful tax advantages for retirement savings, but the choice between a Roth and a traditional IRA involves an important decision about when you’ll pay taxes on that money, now or in retirement, that depends on factors specific to your current and anticipated future financial situation. Understanding the actual mechanics behind each option, rather than defaulting to whichever one a friend happens to use, helps you make a more informed choice for your specific circumstances.
The Core Difference: When You Pay Taxes
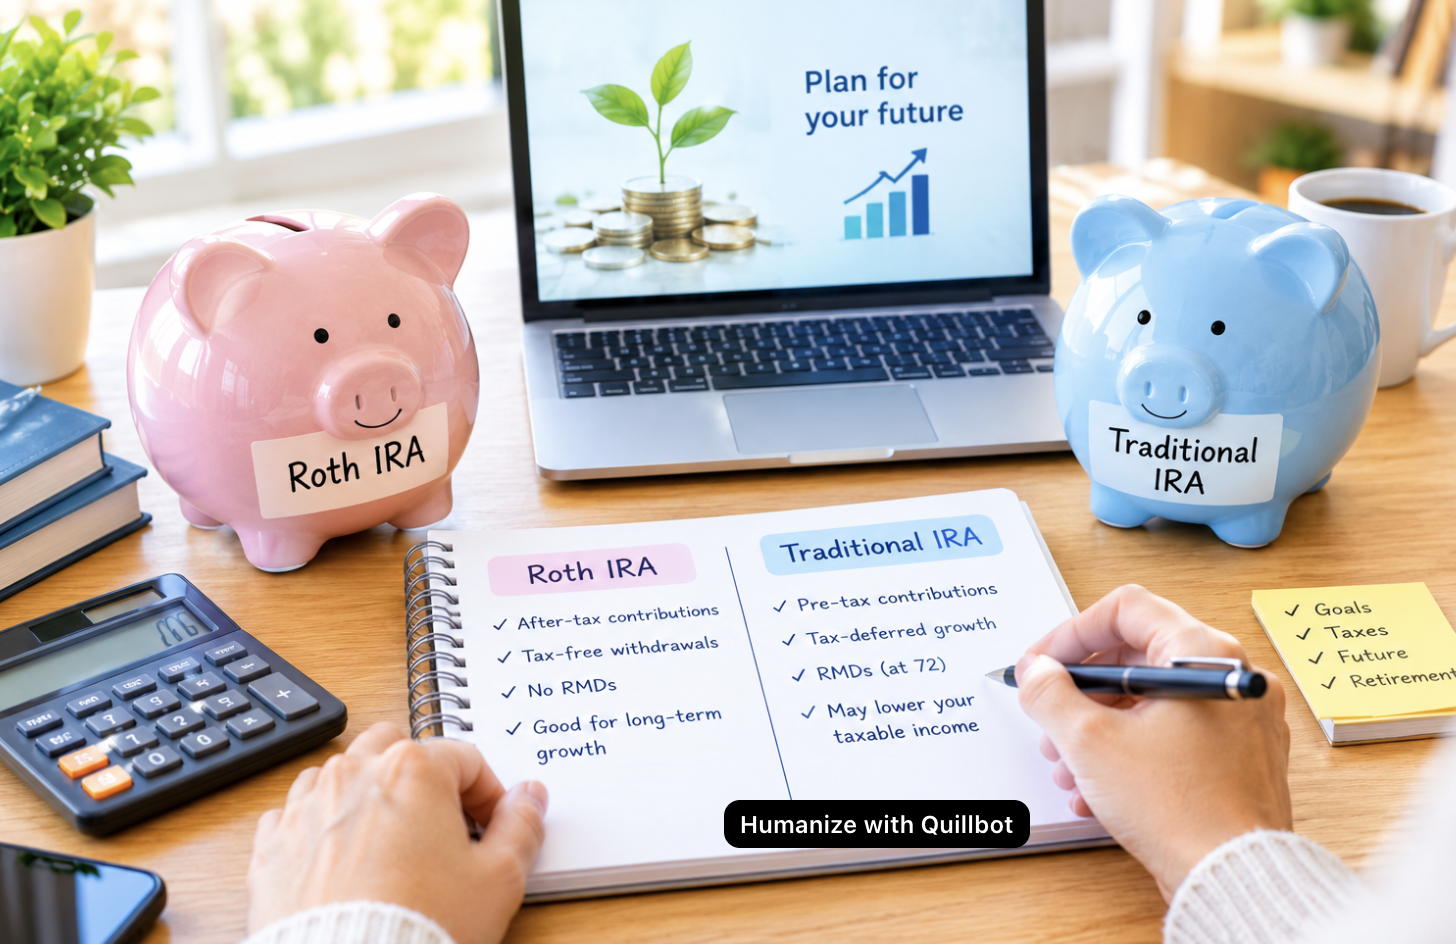
The fundamental distinction between these two account types comes down to timing of taxation. With a traditional IRA, contributions are generally made with pre-tax money, meaning you typically get a tax deduction in the year you contribute, reducing your taxable income for that year. The money then grows tax-deferred, and you pay ordinary income tax on withdrawals during retirement.
With a Roth IRA, contributions are made with money you’ve already paid taxes on, meaning there’s no upfront tax deduction. The benefit comes later, since qualified withdrawals during retirement, including all the investment growth accumulated over the years, are entirely tax-free, rather than being taxed as ordinary income the way traditional IRA withdrawals are.
This core difference, taxed now versus taxed later, is what everything else in the decision ultimately comes back to, and understanding your own situation relative to this tradeoff matters more than any general rule of thumb that doesn’t account for your specific circumstances.
The Key Question: Current vs Future Tax Rate
The theoretically ideal choice depends heavily on whether you expect to be in a higher or lower tax bracket during retirement compared to your current tax bracket while working. If you expect your retirement tax bracket to be lower than your current bracket, perhaps because your income will be lower after leaving the workforce, a traditional IRA’s upfront deduction at your current higher rate, combined with paying tax later at an anticipated lower rate, generally provides more favorable overall tax treatment.
Conversely, if you expect your retirement tax bracket to be similar to or higher than your current bracket, perhaps because you’re early in your career with income likely to grow substantially, or because you anticipate significant retirement income from other sources, a Roth IRA’s tax-free withdrawals become more attractive, since you’re paying tax now at what might be a comparatively lower rate than you’d otherwise pay later.
The challenge here is that predicting your future tax bracket decades in advance involves real uncertainty, both regarding your own personal financial trajectory and potential broader changes to tax policy and rates over time, which is part of why many financial advisors suggest some diversification between both account types rather than committing entirely to one specific prediction about the future.
Consider Your Current Career Stage
Your current point in your career often provides a reasonable, if imperfect, proxy for thinking about this question. Earlier in your career, when your income and corresponding tax bracket are often lower than they’re likely to become later as your career progresses, a Roth IRA becomes more attractive, since you’re paying tax now at a comparatively lower rate while your income has room to grow substantially in the future.
Later in your career, when you may be in a higher tax bracket than you expect to be in during retirement, a traditional IRA’s immediate deduction at your current higher rate becomes comparatively more attractive, assuming your retirement income and corresponding tax bracket will indeed be lower once you’re no longer working.
Understand the Income Limits
Roth IRAs have income limits that can restrict or entirely eliminate your ability to contribute directly if your income exceeds certain thresholds, which adjust periodically and vary based on your tax filing status. Traditional IRAs don’t have income limits on the ability to contribute, though the tax deductibility of your contribution can be limited if you or a spouse have access to an employer-sponsored retirement plan and your income exceeds certain thresholds.
If your income is high enough to be affected by Roth IRA income limits, it’s worth researching the specific current thresholds for your filing status, since this can be a determining factor regardless of your general preference between the two account types, and certain strategies exist for higher earners to still access Roth-style benefits through other structured approaches worth discussing with a financial professional.
Consider Withdrawal Flexibility
Roth IRAs offer somewhat more flexibility around early withdrawals compared to traditional IRAs, since you can generally withdraw your original contributions, though not the investment earnings, at any time without taxes or penalties, since you already paid tax on that contributed money before it went into the account. Traditional IRA withdrawals before retirement age generally face both ordinary income tax and an additional penalty, with certain specific exceptions.
While retirement accounts are designed for long-term retirement savings and withdrawing early generally undermines their core purpose, this added Roth flexibility can matter for some people as a secondary consideration, providing a bit more of a safety net compared to a traditional IRA’s more restrictive early withdrawal rules.
Required Minimum Distributions
Traditional IRAs require you to begin taking required minimum distributions at a certain age, forcing withdrawals, and the associated tax payments, whether or not you actually need the money at that point.
Roth IRAs, for the original account owner, don’t have this requirement during their lifetime, offering more flexibility in how and when you actually access the money during retirement, and potentially more favorable estate planning implications if you’re hoping to pass some retirement savings on to heirs.
You Don’t Necessarily Have to Choose Only One
For many people, particularly those with access to both options and uncertainty about their exact future tax situation, contributing to both a Roth and traditional IRA, splitting contributions between the two rather than committing entirely to one, provides a reasonable hedge against the uncertainty involved in predicting decades into the future.
This diversification of tax treatment, similar in spirit to diversifying investments themselves, means you’re not entirely dependent on correctly predicting your future tax situation to have made the optimal choice.
It’s worth noting that total combined contributions across both a Roth and traditional IRA are still subject to an overall annual contribution limit, so this approach means splitting a single limit between the two accounts rather than doubling your total available contribution room.
When Working With a Financial Professional Makes Sense
Given how much this decision depends on personal factors, your specific income trajectory, anticipated retirement lifestyle, other retirement savings vehicles you have access to, and broader financial planning considerations, consulting with a financial advisor or tax professional, particularly if your situation involves higher income, complex tax considerations, or significant existing retirement savings, can provide more personalized guidance than general information alone can offer.
Conclusion
Given the uncertainty involved in predicting your future tax bracket decades in advance, making a reasonable, well-informed decision based on your current understanding of your career trajectory and financial situation, rather than becoming paralyzed trying to perfectly predict an unknowable future, is a sound approach. Both account types offer meaningful tax-advantaged growth for retirement savings, and starting to contribute consistently to either one, or both, matters considerably more for your long-term financial security than achieving a theoretically perfect choice between them.
Frequently Asked Questions
1. Can I convert a traditional IRA to a Roth IRA later if I change my mind?
Yes, this is called a Roth conversion, and it’s a commonly used strategy, though it does require paying taxes at the time of conversion on any previously untaxed contributions and earnings being converted. This can be a useful strategy in specific situations, such as a lower-income year where the tax cost of converting is comparatively lower, but it’s worth understanding the specific tax implications for your situation before proceeding, ideally with guidance from a tax professional.
2. What happens to my IRA if I have access to a 401k through my employer?
You can generally still contribute to an IRA even with an employer-sponsored plan, though the tax deductibility of traditional IRA contributions may be limited based on your income if you or a spouse are covered by a workplace retirement plan. Roth IRA contribution eligibility is based on income limits rather than workplace plan access specifically, so this consideration mainly affects the traditional IRA side of the decision for those with both types of access.
3. Is there a deadline for contributing to an IRA for a given tax year?
Yes, IRA contributions for a given tax year can generally be made up until the tax filing deadline of the following year, giving you some flexibility to contribute even after the calendar year has ended, provided you do so before the specific filing deadline and clearly designate which tax year the contribution applies to.
4. What if my income is too high to contribute directly to a Roth IRA?
Higher earners who exceed Roth IRA income limits sometimes use a strategy called a backdoor Roth conversion, contributing to a traditional IRA, then converting those funds to a Roth IRA, which isn’t subject to the same income restrictions as direct Roth contributions. This strategy involves specific tax considerations and potential complications depending on your other retirement account holdings, making it worth discussing with a tax professional before implementing.
5. Does it matter which specific investments I hold within a Roth versus traditional IRA?
This is a more advanced consideration, but some financial planners suggest holding investments with higher expected growth potential in a Roth IRA specifically, since all that growth will eventually be withdrawn entirely tax-free, while holding lower-growth investments in a traditional IRA, where the eventual tax bill is based on a potentially smaller total balance. This is a secondary optimization consideration though, and having a reasonable overall investment strategy consistently applied matters more than perfectly optimizing which specific investments sit in which specific account type.
